Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
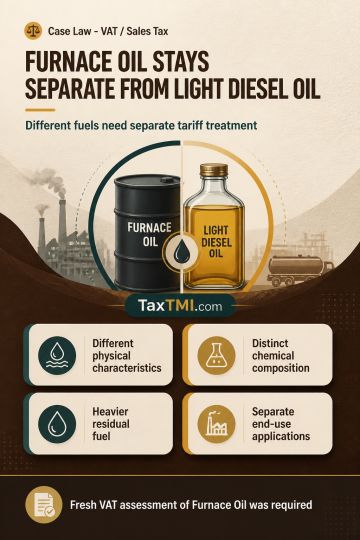
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915