Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
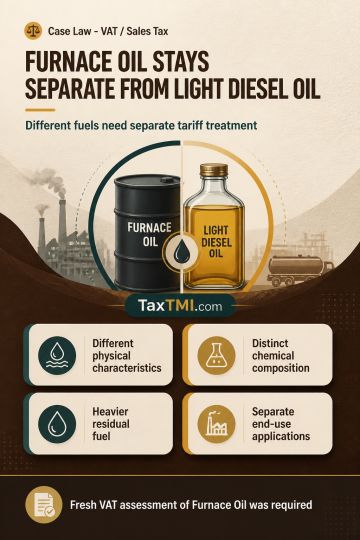
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Furnace Oil and Light Diesel Oil require separate commodity classification where technical specifications show material differences in physical characteristics, composition, distillation range, viscosity and end-use. Furnace Oil is a heavier residual fuel oil, while Light Diesel Oil is a middle distillate and cannot be substituted in engines designed for lighter fuel. A specific tariff entry for Light Diesel Oil cannot be extended to Furnace Oil merely because both are used as fuel, absent a common entry. Classification of Furnace Oil as Light Diesel Oil for VAT levy was set aside, requiring fresh assessment on the basis that the products are distinct commodities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI