Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
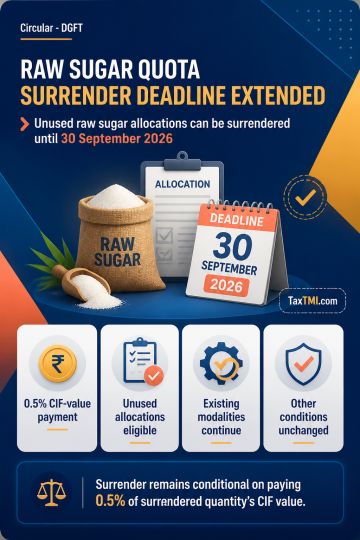
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916