Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
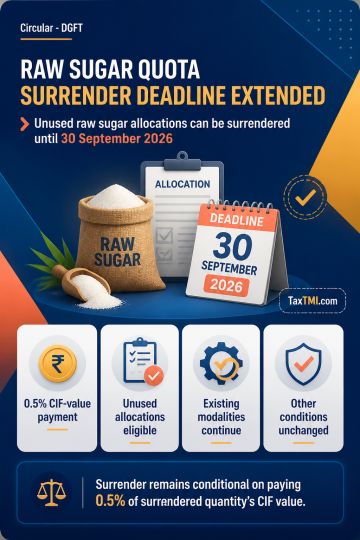
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
TRQ holders allocated raw sugar import quantities may surrender any unutilised allocation until 30 September 2026. Surrender remains subject to payment equal to 0.5% of the CIF value of the quantity surrendered, in accordance with existing modalities. The extension applies to the tariff-rate quota for import of raw sugar, while all other conditions governing the allocation and surrender process remain unchanged.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI