Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
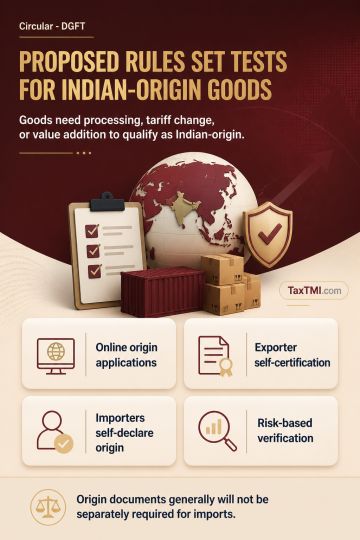
Proposed non-preferential Rules of Origin would require exported goods using imported inputs to undergo processing beyond specified minimal operations before being treated as Indian-origin. Exporters would apply online for non-preferential Certificates of Origin, while manufacturer exporters holding Status Holder recognition could self-certify qualifying goods. Back-to-back certificates could support re-exports, trans-shipment and merchanting trade for foreign-origin goods. For imports, agricultural goods would generally be origin-determined by wholly obtained or produced status, subject to a de-minimis tolerance, while other goods would require either a change in tariff heading or prescribed value addition. Importers would self-declare origin; separate origin documents would generally not be required, with risk-based verification permitted.
Proposed non-preferential Rules of Origin would require exported goods using imported inputs to undergo processing beyond specified minimal operations before being treated as Indian-origin. Exporters would apply online for non-preferential Certificates of Origin, while manufacturer exporters holding Status Holder recognition could self-certify qualifying goods. Back-to-back certificates could support re-exports, trans-shipment and merchanting trade for foreign-origin goods. For imports, agricultural goods would generally be origin-determined by wholly obtained or produced status, subject to a de-minimis tolerance, while other goods would require either a change in tariff heading or prescribed value addition. Importers would self-declare origin; separate origin documents would generally not be required, with risk-based verification permitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916