E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
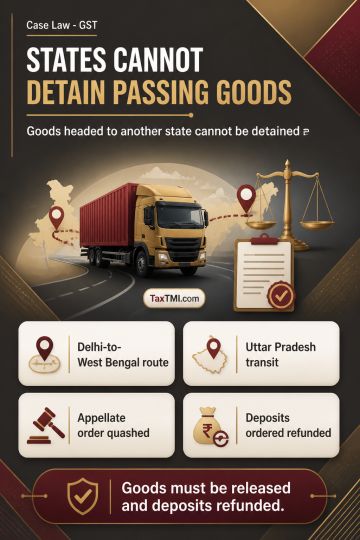
State GST authorities cannot detain or seize goods merely passing through their territory during inter-State transit where the goods are destined for another State. The territorial power to detain and seize does not extend to goods moving from Delhi to West Bengal solely because they transit Uttar Pradesh. On that basis, the appellate order upholding detention was quashed, the goods were directed to be released, and any amount deposited was directed to be refunded.
State GST authorities cannot detain or seize goods merely passing through their territory during inter-State transit where the goods are destined for another State. The territorial power to detain and seize does not extend to goods moving from Delhi to West Bengal solely because they transit Uttar Pradesh. On that basis, the appellate order upholding detention was quashed, the goods were directed to be released, and any amount deposited was directed to be refunded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915