Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
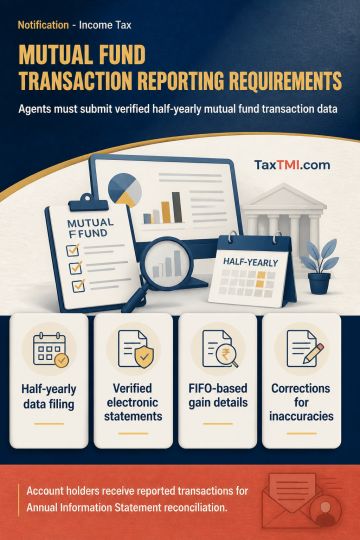
Registrar and Share Transfer Agents registered under the SEBI Act must furnish half-yearly Statements of Financial Transactions for mutual fund transactions in the prescribed electronic format, with a signed and verified control statement. Reporting supports pre-filling of income-tax returns and requires account holders to receive reported transaction information for reconciliation with the Annual Information Statement. Transaction summaries must cover user-initiated debit transactions, apply FIFO to identify corresponding acquisitions and determine holding periods, and classify assets as short-term or long-term under the prescribed security classes. Estimated sale consideration, acquisition cost, grandfathered cost rules and indexation must be reported where applicable. Invalid files are rejected; inaccuracies, defects and deletions require correction or deletion statements. Reporting entities must maintain information-security, archival and retrieval procedures.
Registrar and Share Transfer Agents registered under the SEBI Act must furnish half-yearly Statements of Financial Transactions for mutual fund transactions in the prescribed electronic format, with a signed and verified control statement. Reporting supports pre-filling of income-tax returns and requires account holders to receive reported transaction information for reconciliation with the Annual Information Statement. Transaction summaries must cover user-initiated debit transactions, apply FIFO to identify corresponding acquisitions and determine holding periods, and classify assets as short-term or long-term under the prescribed security classes. Estimated sale consideration, acquisition cost, grandfathered cost rules and indexation must be reported where applicable. Invalid files are rejected; inaccuracies, defects and deletions require correction or deletion statements. Reporting entities must maintain information-security, archival and retrieval procedures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI