Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
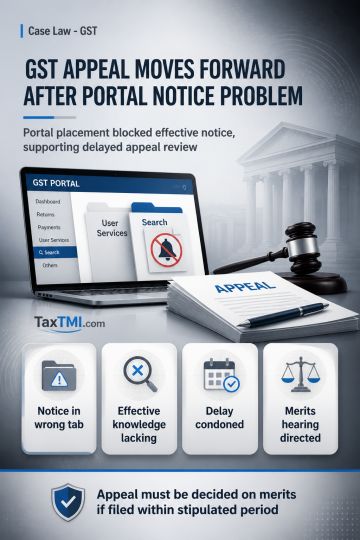
Sufficient cause supported condonation of delay in a GST appeal where the taxpayer lacked effective knowledge of the show-cause notice and adjudication order because they were uploaded under a non-designated portal tab. Although the Appellate Authority remained bound by the limitation prescribed under section 107 of the RGST/CGST Act, circumstances beyond the taxpayer's control and the risk of grave prejudice justified merits review. The delay was condoned, with a direction to entertain and decide the appeal on merits if filed within the stipulated period.
Sufficient cause supported condonation of delay in a GST appeal where the taxpayer lacked effective knowledge of the show-cause notice and adjudication order because they were uploaded under a non-designated portal tab. Although the Appellate Authority remained bound by the limitation prescribed under section 107 of the RGST/CGST Act, circumstances beyond the taxpayer's control and the risk of grave prejudice justified merits review. The delay was condoned, with a direction to entertain and decide the appeal on merits if filed within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915