Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
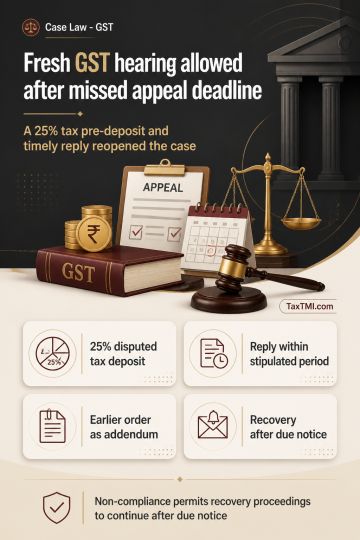
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Fresh adjudication was permitted where the petitioner had not participated in the original proceedings and the statutory appellate limitation had expired. The impugned order was quashed, subject to an additional pre-deposit of 25% of the disputed tax and submission of a reply to the show-cause notice within the stipulated period. The earlier order was to operate as an addendum to the show-cause notice for the fresh proceedings. No further extension or concession was available; failure to comply allowed recovery proceedings to continue in accordance with law after due notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915