Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Page of 4918
Press 'Enter' after typing page number.
1521 to 1540 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
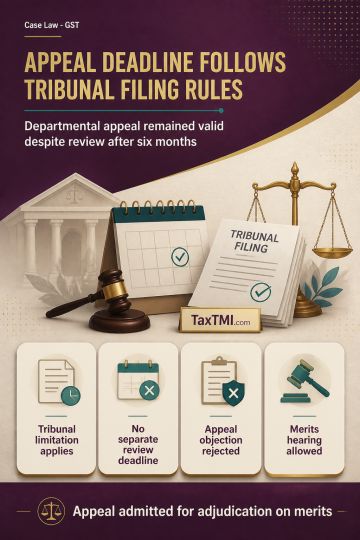
Section 112(3) confines the prescribed limitation period to filing an appeal before the Tribunal and does not impose a separate six-month deadline on the Commissioner to review the first appellate order. A departmental appeal filed within the applicable extended filing period therefore remains maintainable even where the Commissioner's review occurred after six months. The maintainability objection was rejected, and the appeal was admitted for adjudication on merits.
Section 112(3) confines the prescribed limitation period to filing an appeal before the Tribunal and does not impose a separate six-month deadline on the Commissioner to review the first appellate order. A departmental appeal filed within the applicable extended filing period therefore remains maintainable even where the Commissioner's review occurred after six months. The maintainability objection was rejected, and the appeal was admitted for adjudication on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918