Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
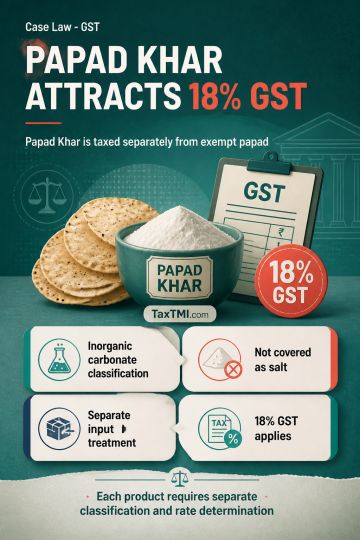
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Papad Khar, an alkaline manufactured mixture containing sodium chloride, sodium carbonate and sodium bicarbonate, is classified as an inorganic carbonate under tariff item 28362090. It is not covered by Heading 2501 because it is neither crude nor merely physically processed salt, and it does not possess the characteristics of yeast or prepared baking powder under Heading 2102. As a Chapter 28 inorganic chemical outside the relevant exclusions and alternative schedules, it attracts GST at 18%. Exemption for exempt papad does not extend automatically to Papad Khar used as an input; each input and finished product requires separate classification and rate determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915