Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
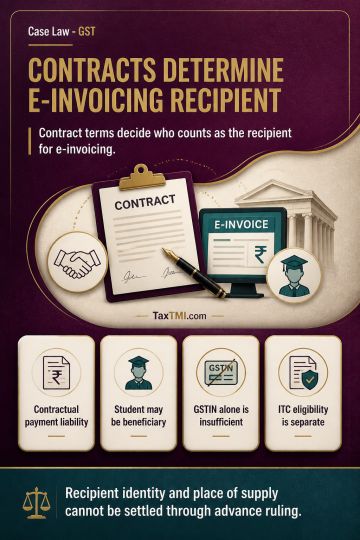
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
E-invoicing applies to coaching-service supplies genuinely made to registered recipients where the supplier falls within the notified class and no exclusion applies. Recipient status depends on an enforceable contractual liability to pay consideration; the student may be the beneficiary, while a parent, guardian or sponsoring enterprise may be the recipient only if contractual terms establish that liability. Mere fee payment or provision of a GSTIN is insufficient. Proposed-supply questions may be raised, but recipient identity and place of supply cannot be determined through advance ruling where they require transaction-specific assessment. Supplier e-invoicing obligations operate independently of the recipient's input tax credit eligibility or business purpose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918