Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
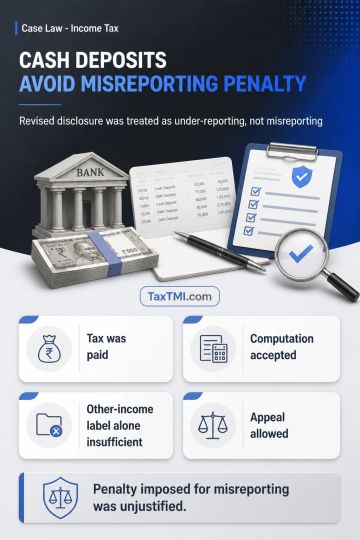
Cash deposits fully disclosed through a revised computation during assessment, with tax paid and the computation accepted, may constitute under-reporting rather than misreporting where the assessment does not identify any statutory ingredient of misreporting. Assessment of the deposits as income from other sources does not itself establish misreporting. On that classification, immunity from penalty for under-reporting is available, and penalty imposed for misreporting is unjustified. The appeal was allowed.
Cash deposits fully disclosed through a revised computation during assessment, with tax paid and the computation accepted, may constitute under-reporting rather than misreporting where the assessment does not identify any statutory ingredient of misreporting. Assessment of the deposits as income from other sources does not itself establish misreporting. On that classification, immunity from penalty for under-reporting is available, and penalty imposed for misreporting is unjustified. The appeal was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915