Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
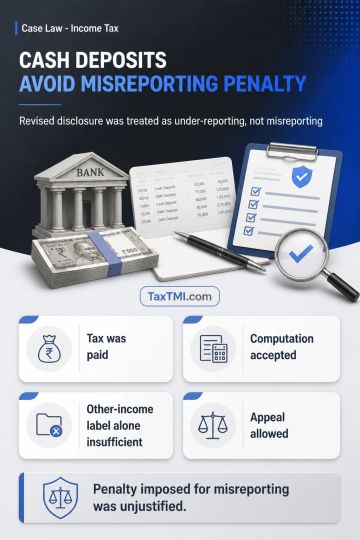
Cash deposits fully disclosed through a revised computation during assessment, with tax paid and the computation accepted, may constitute under-reporting rather than misreporting where the assessment does not identify any statutory ingredient of misreporting. Assessment of the deposits as income from other sources does not itself establish misreporting. On that classification, immunity from penalty for under-reporting is available, and penalty imposed for misreporting is unjustified. The appeal was allowed.
Cash deposits fully disclosed through a revised computation during assessment, with tax paid and the computation accepted, may constitute under-reporting rather than misreporting where the assessment does not identify any statutory ingredient of misreporting. Assessment of the deposits as income from other sources does not itself establish misreporting. On that classification, immunity from penalty for under-reporting is available, and penalty imposed for misreporting is unjustified. The appeal was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915