Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
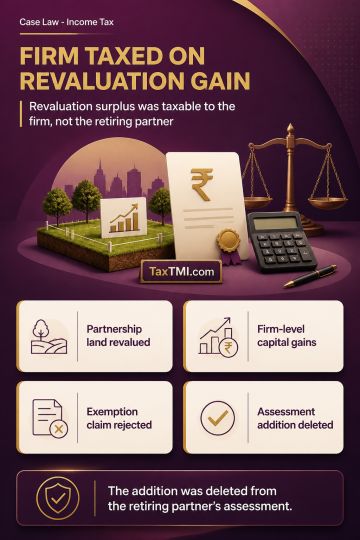
Revaluation surplus credited to a retiring partner following revaluation of partnership land does not constitute the partner's share in the firm's total income and is not exempt under section 10(2A). For the relevant assessment year, distribution of the enhanced value of partnership assets attracted section 45(4), under which the resulting capital gains were taxable in the firm's hands rather than in the retiring partner's hands. The post-1 April 2021 substituted provisions did not apply. Accordingly, the addition of the revaluation surplus in the retiring partner's assessment was deleted, although the exemption claim was rejected.
Revaluation surplus credited to a retiring partner following revaluation of partnership land does not constitute the partner's share in the firm's total income and is not exempt under section 10(2A). For the relevant assessment year, distribution of the enhanced value of partnership assets attracted section 45(4), under which the resulting capital gains were taxable in the firm's hands rather than in the retiring partner's hands. The post-1 April 2021 substituted provisions did not apply. Accordingly, the addition of the revaluation surplus in the retiring partner's assessment was deleted, although the exemption claim was rejected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915