Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Commodity derivatives position limits adopt revised breach penalties, broad commodity criteria, and client open-position limits based on deliverable s...
Page of 4916
Press 'Enter' after typing page number.
1501 to 1520 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
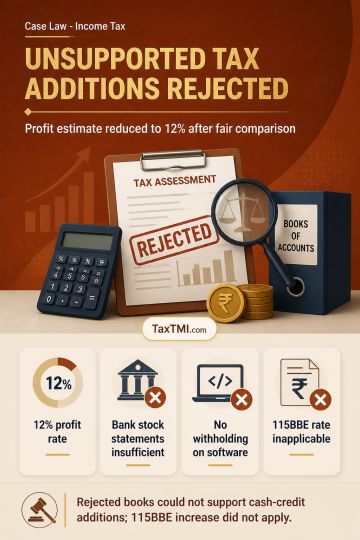
Undisclosed business receipts following rejection of books require profit estimation at a fair rate based on disclosed margins, past results and comparable data; the estimated rate was reduced to 12%. Impounded-document presumptions are rebuttable, and entries cannot be selectively used while corresponding outgoings are ignored; unsupported additions were deleted. Standard off-the-shelf software acquired for internal use without copyright transfer is a goods purchase, so no tax deduction at source applies. Stock statements given to banks, uncorroborated loose-sheet notings and estimated election-expense papers cannot alone establish unexplained investment or expenditure. Rejected books cannot support a separate cash-credit addition after business income is estimated; peak-credit and telescoping claims require reconciliation. The enhanced section 115BBE rate was inapplicable to FY 2016-17 income.
Undisclosed business receipts following rejection of books require profit estimation at a fair rate based on disclosed margins, past results and comparable data; the estimated rate was reduced to 12%. Impounded-document presumptions are rebuttable, and entries cannot be selectively used while corresponding outgoings are ignored; unsupported additions were deleted. Standard off-the-shelf software acquired for internal use without copyright transfer is a goods purchase, so no tax deduction at source applies. Stock statements given to banks, uncorroborated loose-sheet notings and estimated election-expense papers cannot alone establish unexplained investment or expenditure. Rejected books cannot support a separate cash-credit addition after business income is estimated; peak-credit and telescoping claims require reconciliation. The enhanced section 115BBE rate was inapplicable to FY 2016-17 income.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916