Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
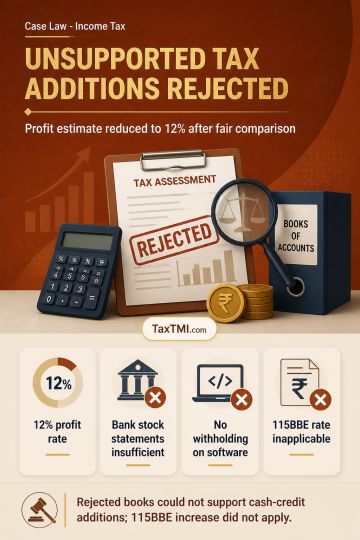
Undisclosed business receipts following rejection of books require profit estimation at a fair rate based on disclosed margins, past results and comparable data; the estimated rate was reduced to 12%. Impounded-document presumptions are rebuttable, and entries cannot be selectively used while corresponding outgoings are ignored; unsupported additions were deleted. Standard off-the-shelf software acquired for internal use without copyright transfer is a goods purchase, so no tax deduction at source applies. Stock statements given to banks, uncorroborated loose-sheet notings and estimated election-expense papers cannot alone establish unexplained investment or expenditure. Rejected books cannot support a separate cash-credit addition after business income is estimated; peak-credit and telescoping claims require reconciliation. The enhanced section 115BBE rate was inapplicable to FY 2016-17 income.
Undisclosed business receipts following rejection of books require profit estimation at a fair rate based on disclosed margins, past results and comparable data; the estimated rate was reduced to 12%. Impounded-document presumptions are rebuttable, and entries cannot be selectively used while corresponding outgoings are ignored; unsupported additions were deleted. Standard off-the-shelf software acquired for internal use without copyright transfer is a goods purchase, so no tax deduction at source applies. Stock statements given to banks, uncorroborated loose-sheet notings and estimated election-expense papers cannot alone establish unexplained investment or expenditure. Rejected books cannot support a separate cash-credit addition after business income is estimated; peak-credit and telescoping claims require reconciliation. The enhanced section 115BBE rate was inapplicable to FY 2016-17 income.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI