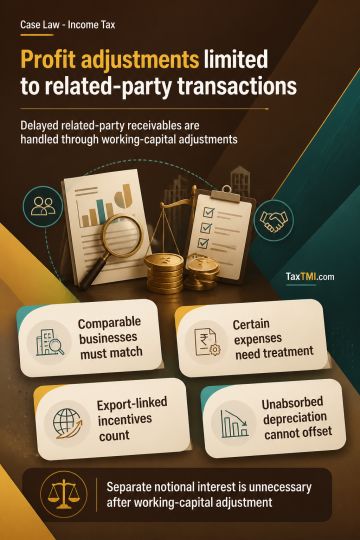
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 41(1) applies only where expenditure or a trading liability was previously allowed as a deduction and the taxpayer subsequently obtains a benefit through remission or cessation. Unpaid interest earlier disallowed under section 43B did not satisfy that condition. Continued balance-sheet recognition, with no write-back, waiver, settlement or discharge, also did not establish cessation; a lender's discounted assignment to an asset reconstruction company did not extinguish the debt. The addition was deleted. Depreciation remained available for a mortgaged building in an existing asset block because mortgage does not transfer ownership and no sale, discard, business unavailability or permanent closure was shown; depreciation was allowed.
Section 41(1) applies only where expenditure or a trading liability was previously allowed as a deduction and the taxpayer subsequently obtains a benefit through remission or cessation. Unpaid interest earlier disallowed under section 43B did not satisfy that condition. Continued balance-sheet recognition, with no write-back, waiver, settlement or discharge, also did not establish cessation; a lender's discounted assignment to an asset reconstruction company did not extinguish the debt. The addition was deleted. Depreciation remained available for a mortgaged building in an existing asset block because mortgage does not transfer ownership and no sale, discard, business unavailability or permanent closure was shown; depreciation was allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921