Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
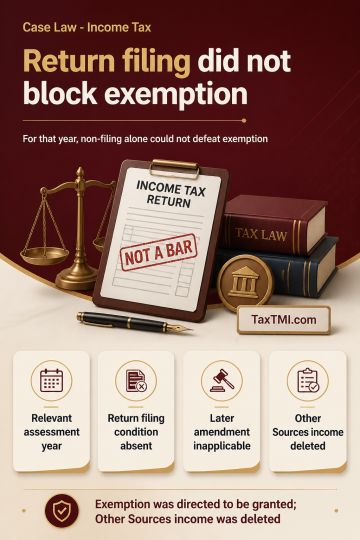
Section 10(23C) exemption for the relevant year did not require return filing by entities outside the categories expressly covered by the Twentieth Proviso. A later amendment imposing a return-filing condition for specified entities could not be applied to that year. Where the revenue authorities did not find that the substantive exemption conditions were unmet, non-filing of a return alone could not defeat the claim. Exemption was consequently directed to be granted in accordance with law, and the income assessed under "Income from Other Sources" was deleted.
Section 10(23C) exemption for the relevant year did not require return filing by entities outside the categories expressly covered by the Twentieth Proviso. A later amendment imposing a return-filing condition for specified entities could not be applied to that year. Where the revenue authorities did not find that the substantive exemption conditions were unmet, non-filing of a return alone could not defeat the claim. Exemption was consequently directed to be granted in accordance with law, and the income assessed under "Income from Other Sources" was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916