Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Page of 4915
Press 'Enter' after typing page number.
1481 to 1500 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
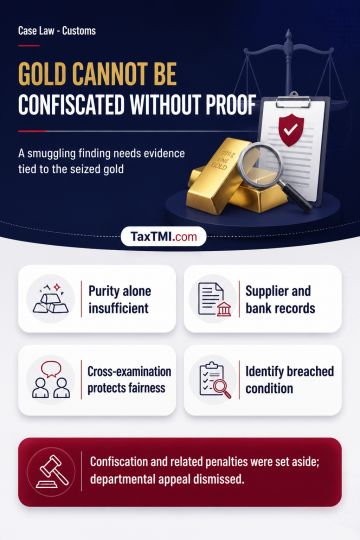
Statutory presumption for notified gold arises only when seizure rests on reasonable belief, supported by objective material, that the particular gold was smuggled. Purity, lack of documents at interception and private carriage do not establish foreign origin. Domestic acquisition may be established through contemporaneous invoices, supplier confirmation and banking records; confiscation for breach of an import exemption condition requires identification of that breached condition. Statements recorded under customs powers remain admissible, but retracted statements require scrutiny of voluntariness, reliability and independent corroboration. Where such statements and a panchanama are challenged, denial of cross-examination of their makers materially prejudices the affected party and violates natural justice. Confiscation and related penalties were set aside, and the departmental appeal was dismissed.
Statutory presumption for notified gold arises only when seizure rests on reasonable belief, supported by objective material, that the particular gold was smuggled. Purity, lack of documents at interception and private carriage do not establish foreign origin. Domestic acquisition may be established through contemporaneous invoices, supplier confirmation and banking records; confiscation for breach of an import exemption condition requires identification of that breached condition. Statements recorded under customs powers remain admissible, but retracted statements require scrutiny of voluntariness, reliability and independent corroboration. Where such statements and a panchanama are challenged, denial of cross-examination of their makers materially prejudices the affected party and violates natural justice. Confiscation and related penalties were set aside, and the departmental appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915