Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
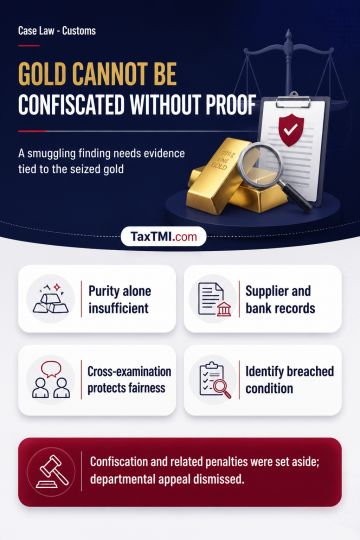
Statutory presumption for notified gold arises only when seizure rests on reasonable belief, supported by objective material, that the particular gold was smuggled. Purity, lack of documents at interception and private carriage do not establish foreign origin. Domestic acquisition may be established through contemporaneous invoices, supplier confirmation and banking records; confiscation for breach of an import exemption condition requires identification of that breached condition. Statements recorded under customs powers remain admissible, but retracted statements require scrutiny of voluntariness, reliability and independent corroboration. Where such statements and a panchanama are challenged, denial of cross-examination of their makers materially prejudices the affected party and violates natural justice. Confiscation and related penalties were set aside, and the departmental appeal was dismissed.
Statutory presumption for notified gold arises only when seizure rests on reasonable belief, supported by objective material, that the particular gold was smuggled. Purity, lack of documents at interception and private carriage do not establish foreign origin. Domestic acquisition may be established through contemporaneous invoices, supplier confirmation and banking records; confiscation for breach of an import exemption condition requires identification of that breached condition. Statements recorded under customs powers remain admissible, but retracted statements require scrutiny of voluntariness, reliability and independent corroboration. Where such statements and a panchanama are challenged, denial of cross-examination of their makers materially prejudices the affected party and violates natural justice. Confiscation and related penalties were set aside, and the departmental appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918