Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Page of 4918
Press 'Enter' after typing page number.
341 to 360 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
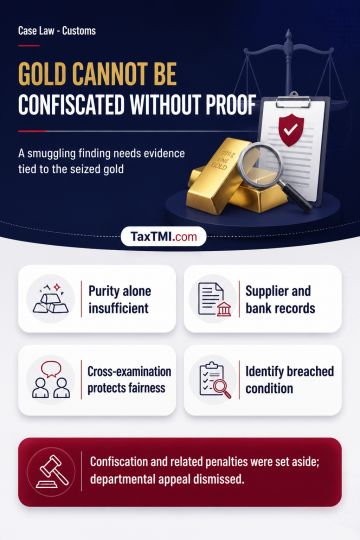
Statutory presumption for notified gold arises only when seizure rests on reasonable belief, supported by objective material, that the particular gold was smuggled. Purity, lack of documents at interception and private carriage do not establish foreign origin. Domestic acquisition may be established through contemporaneous invoices, supplier confirmation and banking records; confiscation for breach of an import exemption condition requires identification of that breached condition. Statements recorded under customs powers remain admissible, but retracted statements require scrutiny of voluntariness, reliability and independent corroboration. Where such statements and a panchanama are challenged, denial of cross-examination of their makers materially prejudices the affected party and violates natural justice. Confiscation and related penalties were set aside, and the departmental appeal was dismissed.
Statutory presumption for notified gold arises only when seizure rests on reasonable belief, supported by objective material, that the particular gold was smuggled. Purity, lack of documents at interception and private carriage do not establish foreign origin. Domestic acquisition may be established through contemporaneous invoices, supplier confirmation and banking records; confiscation for breach of an import exemption condition requires identification of that breached condition. Statements recorded under customs powers remain admissible, but retracted statements require scrutiny of voluntariness, reliability and independent corroboration. Where such statements and a panchanama are challenged, denial of cross-examination of their makers materially prejudices the affected party and violates natural justice. Confiscation and related penalties were set aside, and the departmental appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918