Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Page of 4915
Press 'Enter' after typing page number.
1481 to 1500 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
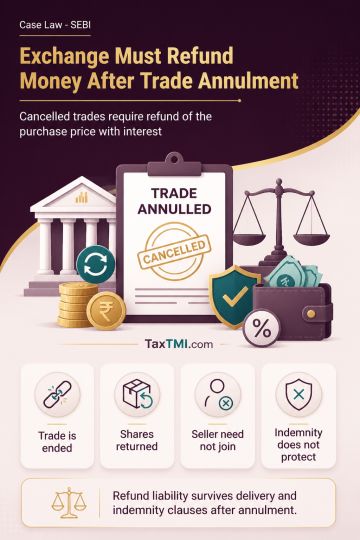
Annulment of a securities trade ends the transaction and makes subsequent physical delivery of the shares purposeless where the shares have been returned to the selling member. The purchaser is entitled to recover the purchase consideration with interest from the Exchange, rather than pursue trading-loss damages. The selling member is not a necessary party because the settlement mechanism creates no direct buyer-seller contract requiring relief against that member after annulment; arbitration and closing-out remedies are therefore inapplicable. An indemnity limited to dispute-resolution references does not grant the Exchange general immunity, and Clearing House non-liability provisions concerning title or validity of securities do not bar refund liability arising from annulment.
Annulment of a securities trade ends the transaction and makes subsequent physical delivery of the shares purposeless where the shares have been returned to the selling member. The purchaser is entitled to recover the purchase consideration with interest from the Exchange, rather than pursue trading-loss damages. The selling member is not a necessary party because the settlement mechanism creates no direct buyer-seller contract requiring relief against that member after annulment; arbitration and closing-out remedies are therefore inapplicable. An indemnity limited to dispute-resolution references does not grant the Exchange general immunity, and Clearing House non-liability provisions concerning title or validity of securities do not bar refund liability arising from annulment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915