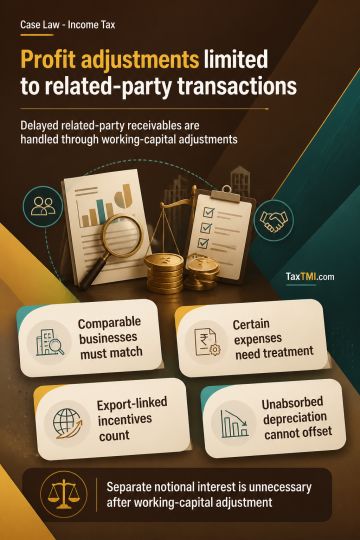
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
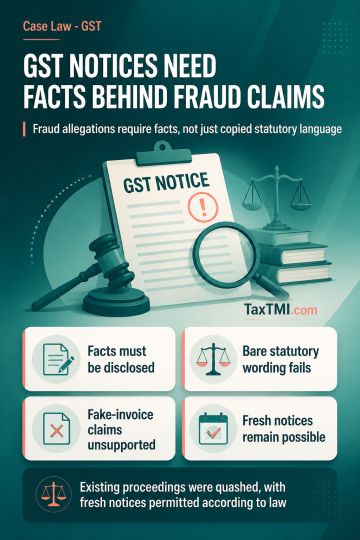
GST notices alleging fraud, wilful misrepresentation or suppression must disclose the foundational facts supporting those allegations. Mere reproduction of statutory expressions, without reasons showing application of mind, does not sustain proceedings alleging input tax credit availed through fake invoices without actual supply of goods. Notices lacking sufficient reasons were quashed, while preserving the authority's liberty to issue fresh notices in accordance with law.
GST notices alleging fraud, wilful misrepresentation or suppression must disclose the foundational facts supporting those allegations. Mere reproduction of statutory expressions, without reasons showing application of mind, does not sustain proceedings alleging input tax credit availed through fake invoices without actual supply of goods. Notices lacking sufficient reasons were quashed, while preserving the authority's liberty to issue fresh notices in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921