Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
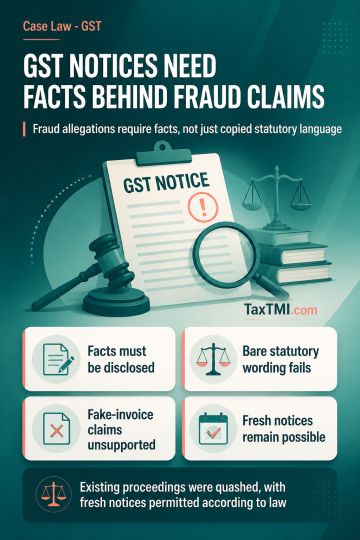
GST notices alleging fraud, wilful misrepresentation or suppression must disclose the foundational facts supporting those allegations. Mere reproduction of statutory expressions, without reasons showing application of mind, does not sustain proceedings alleging input tax credit availed through fake invoices without actual supply of goods. Notices lacking sufficient reasons were quashed, while preserving the authority's liberty to issue fresh notices in accordance with law.
GST notices alleging fraud, wilful misrepresentation or suppression must disclose the foundational facts supporting those allegations. Mere reproduction of statutory expressions, without reasons showing application of mind, does not sustain proceedings alleging input tax credit availed through fake invoices without actual supply of goods. Notices lacking sufficient reasons were quashed, while preserving the authority's liberty to issue fresh notices in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918