Commodity derivatives position limits adopt revised breach penalties, broad commodity criteria, and client open-position limits based on deliverable s...
Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Page of 4918
Press 'Enter' after typing page number.
1561 to 1580 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
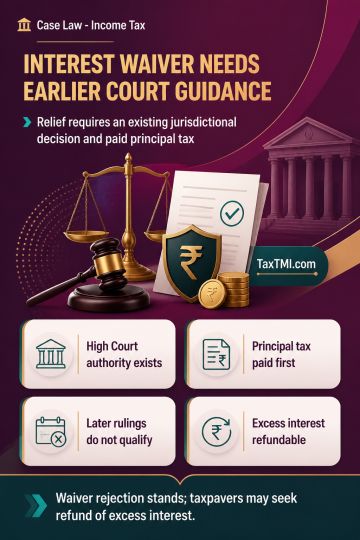
Clause 2(c) of the 2006 interest waiver/reduction scheme requires non-payment of tax to result from a jurisdictional High Court ruling that governed the taxpayer when advance tax was paid or the return was filed. A later ruling does not satisfy that condition, and waiver also requires prior payment of the principal income-tax demand. Challenges to the underlying interest liability cannot be pursued in proceedings confined to a waiver application. Interest under section 220(2) arises only after default in paying a demand served under section 156 within the prescribed period. Waiver rejection was sustained, while taxpayers may seek refund of excess section 220(2) interest if charged from the return-filing date.
Clause 2(c) of the 2006 interest waiver/reduction scheme requires non-payment of tax to result from a jurisdictional High Court ruling that governed the taxpayer when advance tax was paid or the return was filed. A later ruling does not satisfy that condition, and waiver also requires prior payment of the principal income-tax demand. Challenges to the underlying interest liability cannot be pursued in proceedings confined to a waiver application. Interest under section 220(2) arises only after default in paying a demand served under section 156 within the prescribed period. Waiver rejection was sustained, while taxpayers may seek refund of excess section 220(2) interest if charged from the return-filing date.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918