Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
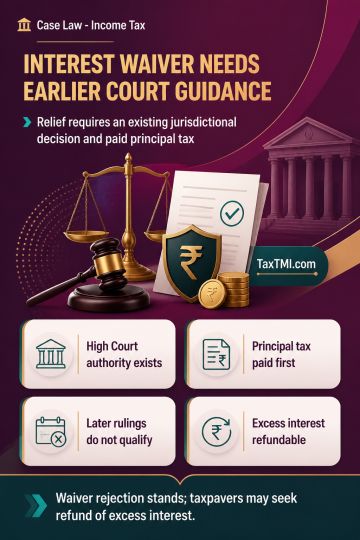
Clause 2(c) of the 2006 interest waiver/reduction scheme requires non-payment of tax to result from a jurisdictional High Court ruling that governed the taxpayer when advance tax was paid or the return was filed. A later ruling does not satisfy that condition, and waiver also requires prior payment of the principal income-tax demand. Challenges to the underlying interest liability cannot be pursued in proceedings confined to a waiver application. Interest under section 220(2) arises only after default in paying a demand served under section 156 within the prescribed period. Waiver rejection was sustained, while taxpayers may seek refund of excess section 220(2) interest if charged from the return-filing date.
Clause 2(c) of the 2006 interest waiver/reduction scheme requires non-payment of tax to result from a jurisdictional High Court ruling that governed the taxpayer when advance tax was paid or the return was filed. A later ruling does not satisfy that condition, and waiver also requires prior payment of the principal income-tax demand. Challenges to the underlying interest liability cannot be pursued in proceedings confined to a waiver application. Interest under section 220(2) arises only after default in paying a demand served under section 156 within the prescribed period. Waiver rejection was sustained, while taxpayers may seek refund of excess section 220(2) interest if charged from the return-filing date.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916