Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
Commodity derivatives position limits adopt revised breach penalties, broad commodity criteria, and client open-position limits based on deliverable s...
Page of 4916
Press 'Enter' after typing page number.
1501 to 1520 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
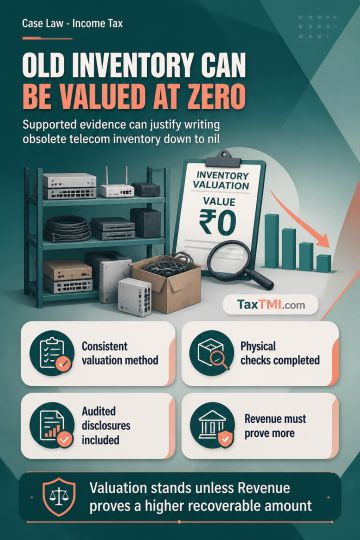
Obsolete telecom-related inventory may be written down to nil under a consistently applied lower-of-cost-or-net-realisable-value method where physical verification, item-wise particulars, audited-account disclosures and business discontinuance support that valuation. Inventory should not be carried above the amount expected from sale or use. A higher assumed scrap or realisable value requires positive evidence, such as an independent valuation, market quotation, comparable sale or identified purchaser; absence of a technical certificate or separate bank communication does not by itself displace a supported valuation. The Revenue bears the burden of proving a higher net realisable value once the valuation basis is reasonably demonstrated.
Obsolete telecom-related inventory may be written down to nil under a consistently applied lower-of-cost-or-net-realisable-value method where physical verification, item-wise particulars, audited-account disclosures and business discontinuance support that valuation. Inventory should not be carried above the amount expected from sale or use. A higher assumed scrap or realisable value requires positive evidence, such as an independent valuation, market quotation, comparable sale or identified purchaser; absence of a technical certificate or separate bank communication does not by itself displace a supported valuation. The Revenue bears the burden of proving a higher net realisable value once the valuation basis is reasonably demonstrated.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916