Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
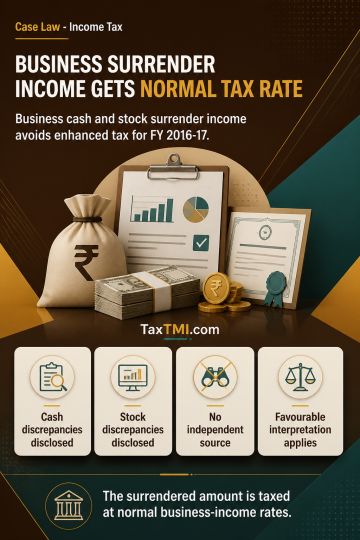
Surrendered income arising from cash and stock discrepancies at business premises, and disclosed in the profit and loss account, is treated as business income where no independent undisclosed asset or non-business source is identified. The enhanced tax rate under section 115BBE, effective from 1 April 2017 without express retrospective operation, does not apply to FY 2016-17. Where competing reasonable interpretations of an ambiguous taxing provision are available and no jurisdictional High Court ruling governs, the interpretation favourable to the assessee applies. The surrendered income is consequently taxable at the normal business-income rate.
Surrendered income arising from cash and stock discrepancies at business premises, and disclosed in the profit and loss account, is treated as business income where no independent undisclosed asset or non-business source is identified. The enhanced tax rate under section 115BBE, effective from 1 April 2017 without express retrospective operation, does not apply to FY 2016-17. Where competing reasonable interpretations of an ambiguous taxing provision are available and no jurisdictional High Court ruling governs, the interpretation favourable to the assessee applies. The surrendered income is consequently taxable at the normal business-income rate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918