Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
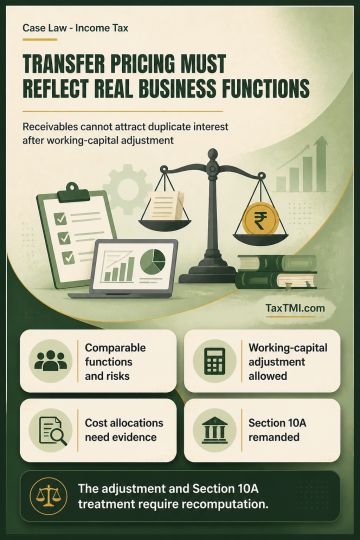
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
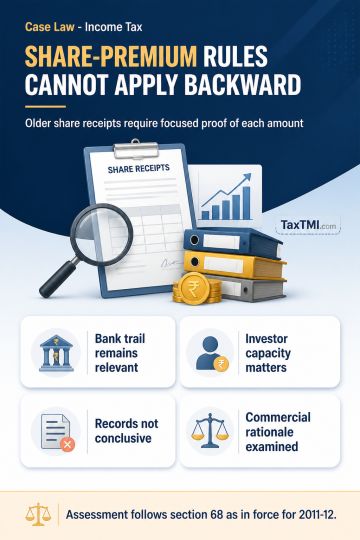
For assessment year 2011-12, subsequently introduced share-premium taxation and the proviso requiring explanation of a resident shareholder's source of funds do not apply retrospectively. Share receipts must instead be tested under section 68 as then in force. Although an assessee has no automatic obligation to prove the source of source, the investor's bank trail, financial capacity, control of funds and surrounding circumstances remain relevant to creditworthiness and genuineness. Where a composite receipt includes share capital, premium, application money and investment-sale consideration, each component requires separate verification. Corporate and banking records are relevant but not conclusive; review should cover investor capacity, antecedent credits, valuation, underlying investments and commercial rationale.
For assessment year 2011-12, subsequently introduced share-premium taxation and the proviso requiring explanation of a resident shareholder's source of funds do not apply retrospectively. Share receipts must instead be tested under section 68 as then in force. Although an assessee has no automatic obligation to prove the source of source, the investor's bank trail, financial capacity, control of funds and surrounding circumstances remain relevant to creditworthiness and genuineness. Where a composite receipt includes share capital, premium, application money and investment-sale consideration, each component requires separate verification. Corporate and banking records are relevant but not conclusive; review should cover investor capacity, antecedent credits, valuation, underlying investments and commercial rationale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918