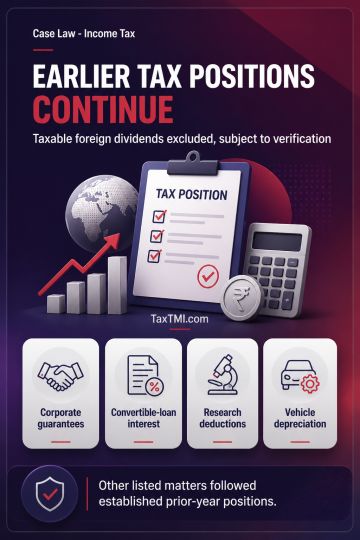
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
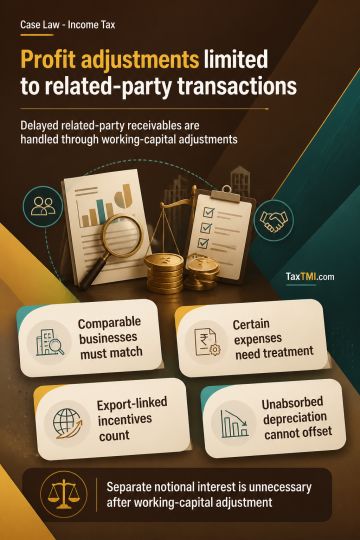
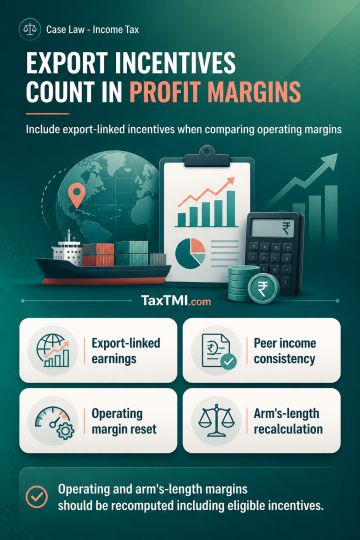
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
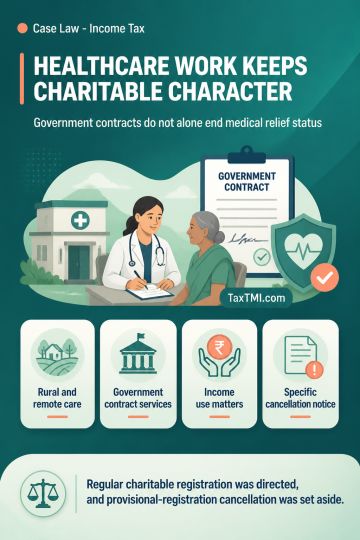
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
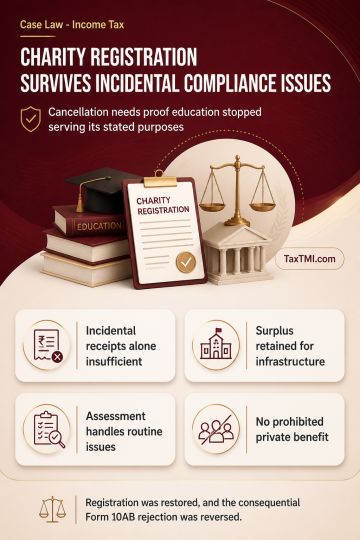
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Page of 4918
Press 'Enter' after typing page number.
1641 to 1660 of 98352 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
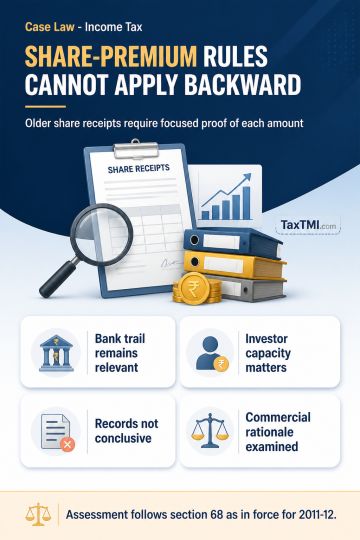
For assessment year 2011-12, subsequently introduced share-premium taxation and the proviso requiring explanation of a resident shareholder's source of funds do not apply retrospectively. Share receipts must instead be tested under section 68 as then in force. Although an assessee has no automatic obligation to prove the source of source, the investor's bank trail, financial capacity, control of funds and surrounding circumstances remain relevant to creditworthiness and genuineness. Where a composite receipt includes share capital, premium, application money and investment-sale consideration, each component requires separate verification. Corporate and banking records are relevant but not conclusive; review should cover investor capacity, antecedent credits, valuation, underlying investments and commercial rationale.
For assessment year 2011-12, subsequently introduced share-premium taxation and the proviso requiring explanation of a resident shareholder's source of funds do not apply retrospectively. Share receipts must instead be tested under section 68 as then in force. Although an assessee has no automatic obligation to prove the source of source, the investor's bank trail, financial capacity, control of funds and surrounding circumstances remain relevant to creditworthiness and genuineness. Where a composite receipt includes share capital, premium, application money and investment-sale consideration, each component requires separate verification. Corporate and banking records are relevant but not conclusive; review should cover investor capacity, antecedent credits, valuation, underlying investments and commercial rationale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918