Reassessment for unreturned property sales survives where transfer information, non-filing, and unsupported exemption claims establish a prima facie l...
Profit-element taxation limits additions for unaccounted flat-sale receipts and grey-market purchases, while reliable search records support partial a...
Non-participating bidders cannot disturb concluded liquidation sales on speculative prejudice, while costs for such challenges must remain proportiona...
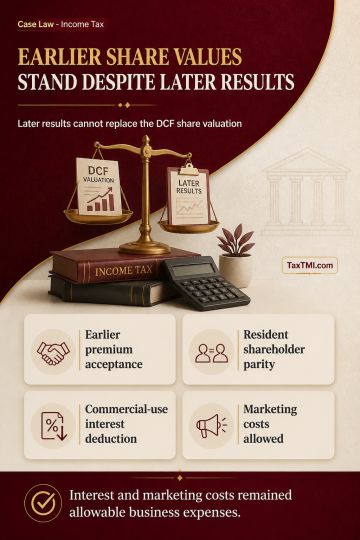
DCF valuation adopted for share premium under Rule 11UA cannot be replaced by the NAV method merely because projected results differ from subsequent actual performance. Consistent acceptance of the same premium in earlier years and for identical shares issued to non-residents supports equivalent treatment for resident shareholders. Occupancy certificates do not determine the deductibility of borrowing interest where commercial buildings have been put to use, rental income is assessed as business income, and borrowings funded construction. Advertisement and marketing costs for commercial space remain allowable business expenditure where incurred for commercial exploitation, notwithstanding a subsequently obtained occupancy certificate.
DCF valuation adopted for share premium under Rule 11UA cannot be replaced by the NAV method merely because projected results differ from subsequent actual performance. Consistent acceptance of the same premium in earlier years and for identical shares issued to non-residents supports equivalent treatment for resident shareholders. Occupancy certificates do not determine the deductibility of borrowing interest where commercial buildings have been put to use, rental income is assessed as business income, and borrowings funded construction. Advertisement and marketing costs for commercial space remain allowable business expenditure where incurred for commercial exploitation, notwithstanding a subsequently obtained occupancy certificate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927