Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
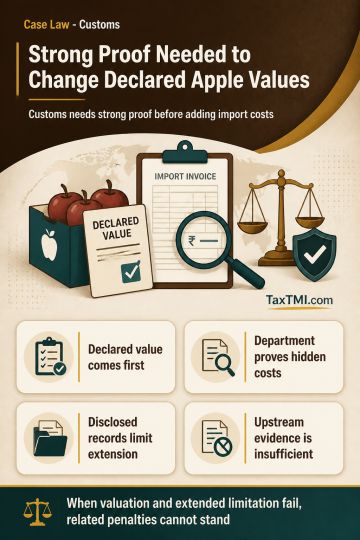
Customs valuation of CIF-imported fresh apples must begin with the declared transaction value, which may be rejected only on cogent evidence that it does not reflect the price actually paid or payable. The Department bears the burden of proving undisclosed additional consideration; an upstream FOB transaction, prepaid freight, Non-GMO certificates, and uncorroborated statements do not by themselves establish omitted freight, insurance, or a different CIF consideration. Disclosure of import documents and the CIF Incoterm precludes extended limitation absent deliberate collusion, wilful misstatement, or suppression intended to evade duty. Where valuation and extended limitation fail, enhancement, value-based confiscation, redemption fine, and related penalties cannot stand.
Customs valuation of CIF-imported fresh apples must begin with the declared transaction value, which may be rejected only on cogent evidence that it does not reflect the price actually paid or payable. The Department bears the burden of proving undisclosed additional consideration; an upstream FOB transaction, prepaid freight, Non-GMO certificates, and uncorroborated statements do not by themselves establish omitted freight, insurance, or a different CIF consideration. Disclosure of import documents and the CIF Incoterm precludes extended limitation absent deliberate collusion, wilful misstatement, or suppression intended to evade duty. Where valuation and extended limitation fail, enhancement, value-based confiscation, redemption fine, and related penalties cannot stand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915