Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
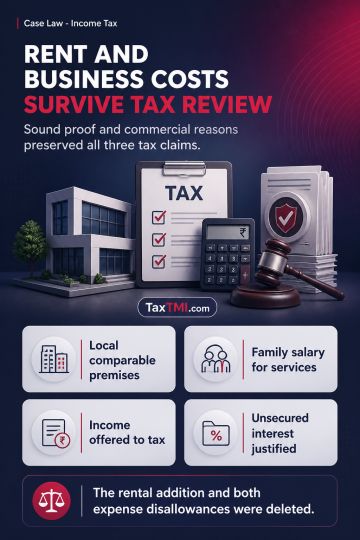
Rental income valuation requires credible local comparables; family-business salary and commercially expedient unsecured-loan interest remained deduct...
Return filed in response to a reassessment notice may be treated as a regular return where delayed filing was bona fide because an advance-ruling application on the taxability of the sole transaction remained pending. Credit of tax deducted at source and other prepaid taxes must be allowed against the assessed demand; once such adjustment is permissible, excess prepaid tax cannot be denied as a refund without statutory basis. Fresh assessment must verify the prepaid-tax credits, grant any resulting refund with applicable interest, and may entail fresh penalty proceedings where warranted.
Return filed in response to a reassessment notice may be treated as a regular return where delayed filing was bona fide because an advance-ruling application on the taxability of the sole transaction remained pending. Credit of tax deducted at source and other prepaid taxes must be allowed against the assessed demand; once such adjustment is permissible, excess prepaid tax cannot be denied as a refund without statutory basis. Fresh assessment must verify the prepaid-tax credits, grant any resulting refund with applicable interest, and may entail fresh penalty proceedings where warranted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921