Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
Page of 4918
Press 'Enter' after typing page number.
101 to 120 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Transfer-pricing treatment of corporate guarantees and interest...
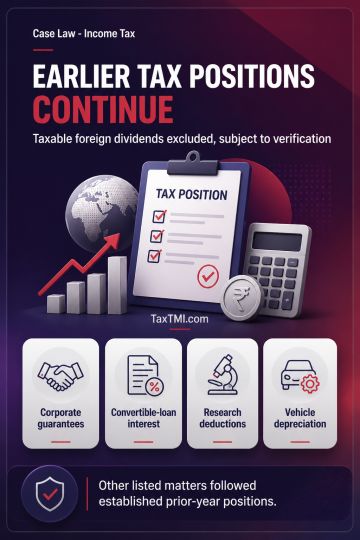
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from exempt-income calculations.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing treatment of corporate guarantees and interest on convertible loans followed consistent prior-year treatment where no factual difference was shown. Payments to non-residents, product, trademark and patent registration expenses, in-house research and development deductions, vehicle depreciation, and partner remuneration were also addressed through established prior-year positions. Exempt-income expenditure disallowance is computed only by reference to investments yielding exempt income; foreign investments generating taxable dividends require exclusion, subject to verification. Foreign-currency royalty receipts already recorded and offered to tax cannot be treated as undisclosed income without supporting material. Employee contributions already disallowed by the taxpayer cannot be disallowed again.
Transfer-pricing treatment of corporate guarantees and interest on convertible loans followed consistent prior-year treatment where no factual difference was shown. Payments to non-residents, product, trademark and patent registration expenses, in-house research and development deductions, vehicle depreciation, and partner remuneration were also addressed through established prior-year positions. Exempt-income expenditure disallowance is computed only by reference to investments yielding exempt income; foreign investments generating taxable dividends require exclusion, subject to verification. Foreign-currency royalty receipts already recorded and offered to tax cannot be treated as undisclosed income without supporting material. Employee contributions already disallowed by the taxpayer cannot be disallowed again.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918