Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Chapter X confines transfer-pricing adjustments to income from...
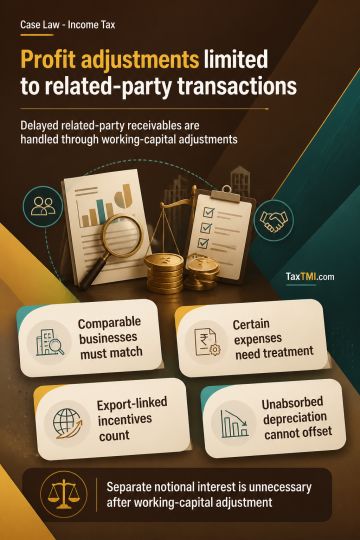
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capital adjustments.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Chapter X confines transfer-pricing adjustments to income from international transactions with associated enterprises and does not permit entity-level enhancement of profits from unrelated-party dealings. Under TNMM, operating margins must reflect appropriate treatment of non-operating marketing and promotional expenses, warranty provisions and bad debts, while business liability write-backs and export incentives linked to export sales are operating income; other operating income must not be excluded twice. Comparable selection for Air Handling Unit manufacturers depends on functional similarity, retaining industrial HVAC and refrigeration manufacturers but excluding final consumer, commercial refrigeration, or mobility-product businesses. Delayed associated-enterprise receivables linked to goods sales require combined benchmarking; a working-capital adjustment removes the need for separate notional interest. Brought-forward unabsorbed depreciation cannot be set off against income from other sources.
Chapter X confines transfer-pricing adjustments to income from international transactions with associated enterprises and does not permit entity-level enhancement of profits from unrelated-party dealings. Under TNMM, operating margins must reflect appropriate treatment of non-operating marketing and promotional expenses, warranty provisions and bad debts, while business liability write-backs and export incentives linked to export sales are operating income; other operating income must not be excluded twice. Comparable selection for Air Handling Unit manufacturers depends on functional similarity, retaining industrial HVAC and refrigeration manufacturers but excluding final consumer, commercial refrigeration, or mobility-product businesses. Delayed associated-enterprise receivables linked to goods sales require combined benchmarking; a working-capital adjustment removes the need for separate notional interest. Brought-forward unabsorbed depreciation cannot be set off against income from other sources.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921