Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
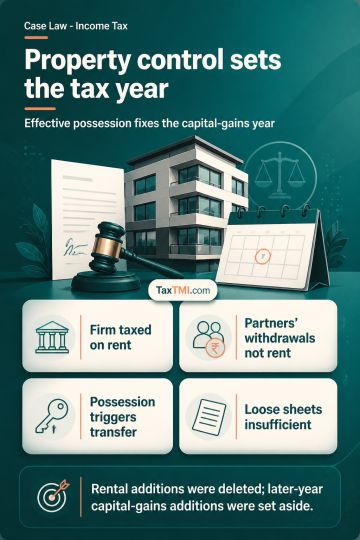
Rental receipts credited, accounted for and assessed in a registered partnership firm's hands remain taxable to the firm; partners' capital-account withdrawals do not constitute rental income or transfer ownership of the building. Under a registered joint development agreement granting the developer effective possession, dominion and authority over the property, transfer occurs on execution of the agreement rather than on later delivery of constructed area. The special capital-gains regime for joint development agreements operates prospectively and does not apply to earlier transactions. Rough, unparticularised loose sheets without independent corroboration cannot support additions for undisclosed or underreported rental income. The rental-income additions were deleted and later-year capital-gains additions were set aside.
Rental receipts credited, accounted for and assessed in a registered partnership firm's hands remain taxable to the firm; partners' capital-account withdrawals do not constitute rental income or transfer ownership of the building. Under a registered joint development agreement granting the developer effective possession, dominion and authority over the property, transfer occurs on execution of the agreement rather than on later delivery of constructed area. The special capital-gains regime for joint development agreements operates prospectively and does not apply to earlier transactions. Rough, unparticularised loose sheets without independent corroboration cannot support additions for undisclosed or underreported rental income. The rental-income additions were deleted and later-year capital-gains additions were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918