Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Page of 4916
Press 'Enter' after typing page number.
41 to 60 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
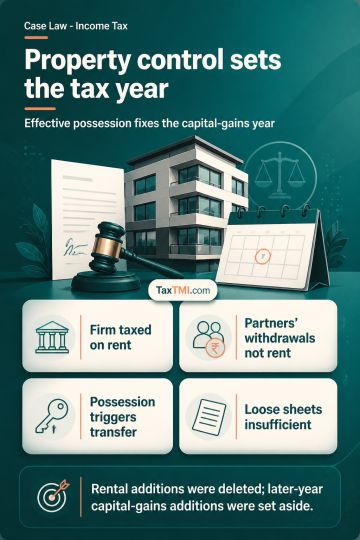
Rental receipts credited, accounted for and assessed in a registered partnership firm's hands remain taxable to the firm; partners' capital-account withdrawals do not constitute rental income or transfer ownership of the building. Under a registered joint development agreement granting the developer effective possession, dominion and authority over the property, transfer occurs on execution of the agreement rather than on later delivery of constructed area. The special capital-gains regime for joint development agreements operates prospectively and does not apply to earlier transactions. Rough, unparticularised loose sheets without independent corroboration cannot support additions for undisclosed or underreported rental income. The rental-income additions were deleted and later-year capital-gains additions were set aside.
Rental receipts credited, accounted for and assessed in a registered partnership firm's hands remain taxable to the firm; partners' capital-account withdrawals do not constitute rental income or transfer ownership of the building. Under a registered joint development agreement granting the developer effective possession, dominion and authority over the property, transfer occurs on execution of the agreement rather than on later delivery of constructed area. The special capital-gains regime for joint development agreements operates prospectively and does not apply to earlier transactions. Rough, unparticularised loose sheets without independent corroboration cannot support additions for undisclosed or underreported rental income. The rental-income additions were deleted and later-year capital-gains additions were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916