Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
Medical relief includes mobile healthcare services delivered to...
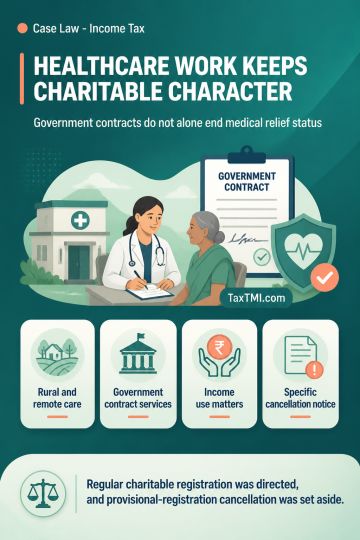
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation requires specific notice.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Medical relief includes mobile healthcare services delivered to rural and remote populations under Government contracts where the objects remain exclusively charitable and prohibit commercial operation. Contractual receipts, tax deduction at source and surplus generation do not alone convert such activities into business; the decisive considerations are the institution's purpose and deployment of income. Regular charitable registration cannot be refused merely because beneficiary records are held by the Government or payments are made to related persons, absent proof that payments were excessive or unreasonable for services rendered. Cancellation of provisional registration requires specific notice of the statutory ground and an effective opportunity to respond. Regular registration was directed, and the provisional-registration cancellation was set aside.
Medical relief includes mobile healthcare services delivered to rural and remote populations under Government contracts where the objects remain exclusively charitable and prohibit commercial operation. Contractual receipts, tax deduction at source and surplus generation do not alone convert such activities into business; the decisive considerations are the institution's purpose and deployment of income. Regular charitable registration cannot be refused merely because beneficiary records are held by the Government or payments are made to related persons, absent proof that payments were excessive or unreasonable for services rendered. Cancellation of provisional registration requires specific notice of the statutory ground and an effective opportunity to respond. Regular registration was directed, and the provisional-registration cancellation was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915