Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Section 12AB cancellation requires cogent material showing that...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are insufficient.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
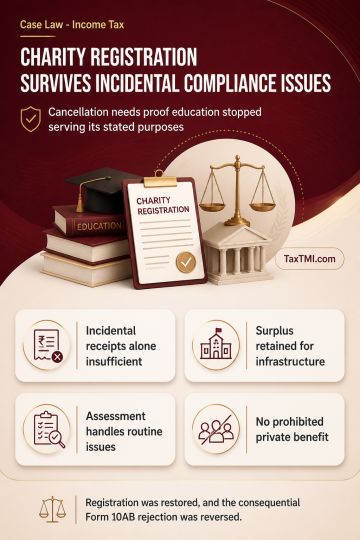
Section 12AB cancellation requires cogent material showing that charitable activities are not genuine, depart from stated objects, or meet another specified statutory ground. Deficiencies concerning expenditure, application of income, investments or compliance with other laws ordinarily belong in assessment proceedings unless they establish abandonment of charitable purposes. Incidental examination and mobile-tower receipts, educational surplus retained for infrastructure, an unregistered lease, and family management without prohibited private benefit do not alone establish profiteering or specified violations. Registration was restored, and the consequential Form 10AB rejection, based solely on cancellation, was reversed with a direction to grant appropriate registration.
Section 12AB cancellation requires cogent material showing that charitable activities are not genuine, depart from stated objects, or meet another specified statutory ground. Deficiencies concerning expenditure, application of income, investments or compliance with other laws ordinarily belong in assessment proceedings unless they establish abandonment of charitable purposes. Incidental examination and mobile-tower receipts, educational surplus retained for infrastructure, an unregistered lease, and family management without prohibited private benefit do not alone establish profiteering or specified violations. Registration was restored, and the consequential Form 10AB rejection, based solely on cancellation, was reversed with a direction to grant appropriate registration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI