Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
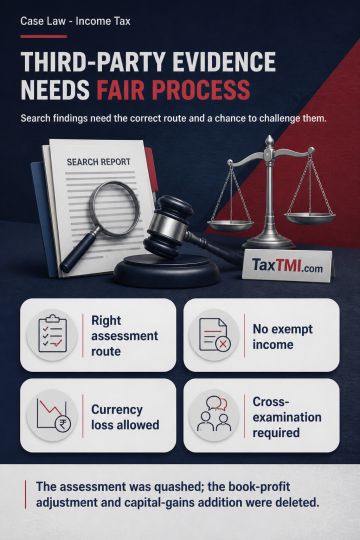
Search material found at a third party's premises must be used for assessment or reassessment under section 153C, not a regular section 143(3) assessment; where the relevant assessment was pending and abated, the section 143(3) assessment was invalid and quashed. Section 14A read with rule 8D does not permit expenditure disallowance without exempt income, and the corresponding book-profit adjustment was deleted. Foreign-exchange loss on revenue-account liabilities, recognised under Accounting Standard-11, is allowable as business expenditure. An addition based solely on undisclosed third-party material, without disclosure or cross-examination, breaches natural justice; search presumptions do not apply against the assessee, and the capital-gains addition was deleted.
Search material found at a third party's premises must be used for assessment or reassessment under section 153C, not a regular section 143(3) assessment; where the relevant assessment was pending and abated, the section 143(3) assessment was invalid and quashed. Section 14A read with rule 8D does not permit expenditure disallowance without exempt income, and the corresponding book-profit adjustment was deleted. Foreign-exchange loss on revenue-account liabilities, recognised under Accounting Standard-11, is allowable as business expenditure. An addition based solely on undisclosed third-party material, without disclosure or cross-examination, breaches natural justice; search presumptions do not apply against the assessee, and the capital-gains addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916