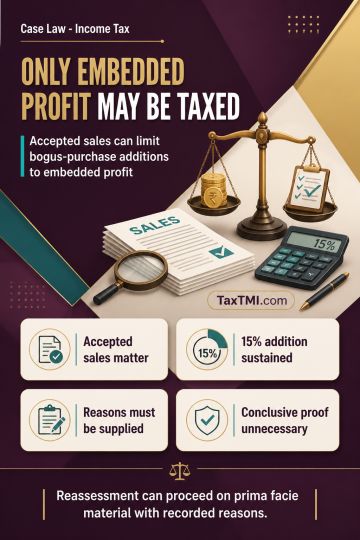
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
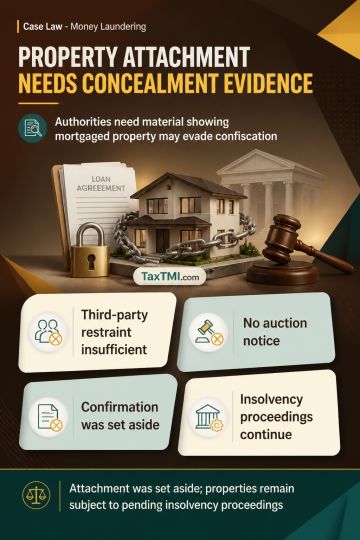
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Statutory limitation for GST appeals under section 107 bound the appellate authority, but the High Court condoned delay where circumstances beyond the taxpayer's control prevented timely filing and refusal of merits review would cause grave injury and prejudice. The appellate order dismissing the appeal as time-barred was set aside. The GST appeal concerning alleged wrongful availment of input tax credit was permitted to be filed and decided on merits without limitation objection, subject to compliance with the filing period stipulated by the High Court.
Statutory limitation for GST appeals under section 107 bound the appellate authority, but the High Court condoned delay where circumstances beyond the taxpayer's control prevented timely filing and refusal of merits review would cause grave injury and prejudice. The appellate order dismissing the appeal as time-barred was set aside. The GST appeal concerning alleged wrongful availment of input tax credit was permitted to be filed and decided on merits without limitation objection, subject to compliance with the filing period stipulated by the High Court.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918