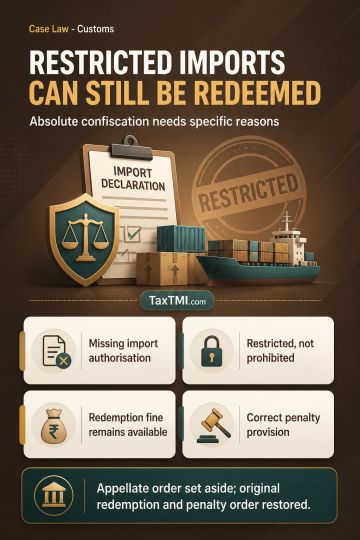
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
Page of 4916
Press 'Enter' after typing page number.
1721 to 1740 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Statutory limitation for GST appeals under section 107 bound the appellate authority, but the High Court condoned delay where circumstances beyond the taxpayer's control prevented timely filing and refusal of merits review would cause grave injury and prejudice. The appellate order dismissing the appeal as time-barred was set aside. The GST appeal concerning alleged wrongful availment of input tax credit was permitted to be filed and decided on merits without limitation objection, subject to compliance with the filing period stipulated by the High Court.
Statutory limitation for GST appeals under section 107 bound the appellate authority, but the High Court condoned delay where circumstances beyond the taxpayer's control prevented timely filing and refusal of merits review would cause grave injury and prejudice. The appellate order dismissing the appeal as time-barred was set aside. The GST appeal concerning alleged wrongful availment of input tax credit was permitted to be filed and decided on merits without limitation objection, subject to compliance with the filing period stipulated by the High Court.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916