Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Transfer-pricing benchmarking of back-office support services...
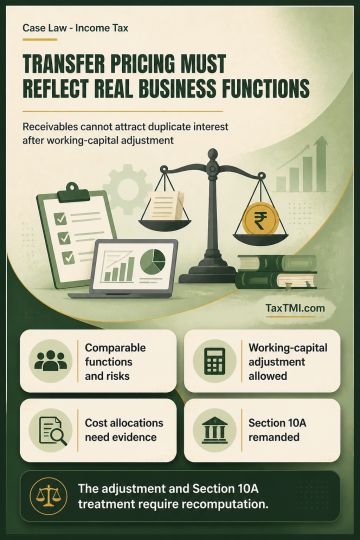
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise receivables.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing benchmarking of back-office support services requires comparables with similar functions and risk profiles; specialised engineering, knowledge-process, outsourced, geographically distinct businesses and entities affected by extraordinary events were excluded, while one comparable was retained, requiring recomputation of the adjustment. A low-risk captive service provider is entitled to a working-capital adjustment on furnishing supporting computations. Separate notional interest on associated-enterprise receivables cannot be charged where receivables are already reflected in working-capital adjustment and service pricing, as this duplicates the adjustment. Associated-enterprise cost allocations incurred without mark-up cannot be assigned a nil arm's length price absent evidence that services were not rendered or had nil cost. Unbilled revenue treatment for section 10A was remanded for recomputation.
Transfer-pricing benchmarking of back-office support services requires comparables with similar functions and risk profiles; specialised engineering, knowledge-process, outsourced, geographically distinct businesses and entities affected by extraordinary events were excluded, while one comparable was retained, requiring recomputation of the adjustment. A low-risk captive service provider is entitled to a working-capital adjustment on furnishing supporting computations. Separate notional interest on associated-enterprise receivables cannot be charged where receivables are already reflected in working-capital adjustment and service pricing, as this duplicates the adjustment. Associated-enterprise cost allocations incurred without mark-up cannot be assigned a nil arm's length price absent evidence that services were not rendered or had nil cost. Unbilled revenue treatment for section 10A was remanded for recomputation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915