Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Page of 4918
Press 'Enter' after typing page number.
1321 to 1340 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Transfer-pricing benchmarking of back-office support services...
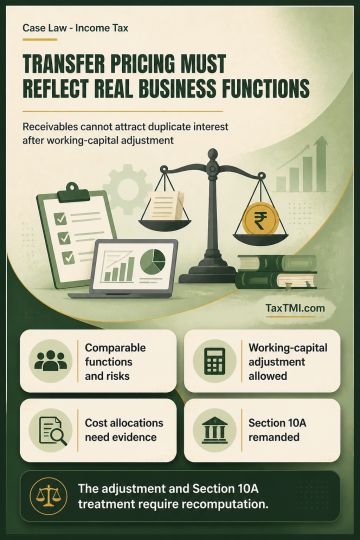
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise receivables.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing benchmarking of back-office support services requires comparables with similar functions and risk profiles; specialised engineering, knowledge-process, outsourced, geographically distinct businesses and entities affected by extraordinary events were excluded, while one comparable was retained, requiring recomputation of the adjustment. A low-risk captive service provider is entitled to a working-capital adjustment on furnishing supporting computations. Separate notional interest on associated-enterprise receivables cannot be charged where receivables are already reflected in working-capital adjustment and service pricing, as this duplicates the adjustment. Associated-enterprise cost allocations incurred without mark-up cannot be assigned a nil arm's length price absent evidence that services were not rendered or had nil cost. Unbilled revenue treatment for section 10A was remanded for recomputation.
Transfer-pricing benchmarking of back-office support services requires comparables with similar functions and risk profiles; specialised engineering, knowledge-process, outsourced, geographically distinct businesses and entities affected by extraordinary events were excluded, while one comparable was retained, requiring recomputation of the adjustment. A low-risk captive service provider is entitled to a working-capital adjustment on furnishing supporting computations. Separate notional interest on associated-enterprise receivables cannot be charged where receivables are already reflected in working-capital adjustment and service pricing, as this duplicates the adjustment. Associated-enterprise cost allocations incurred without mark-up cannot be assigned a nil arm's length price absent evidence that services were not rendered or had nil cost. Unbilled revenue treatment for section 10A was remanded for recomputation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918