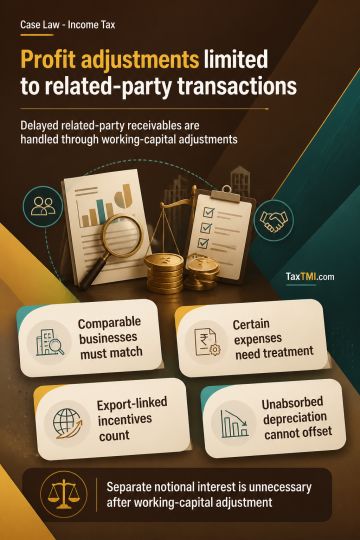
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
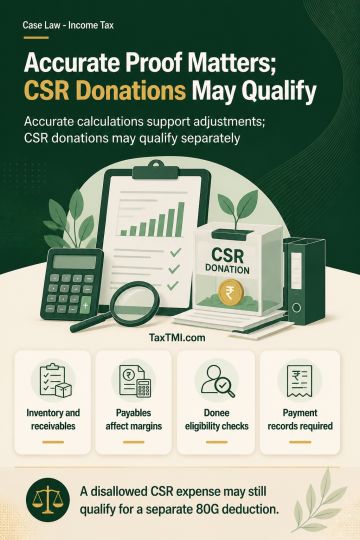
Working capital adjustment in transfer pricing may neutralise margin differences arising from inventory, trade receivables and trade payables through the time value of funds. Rule 10B(3) permits adjustment where a difference materially affects price, cost or profit and can be eliminated by a reasonably accurate computation. Verification of the taxpayer's computation and supporting material is required before granting the adjustment. A CSR contribution disallowed as business expenditure may nevertheless qualify for a separate section 80G deduction. An appellate authority may entertain an additional claim arising from facts already on record, subject to verification of the donee's eligibility, payment, prescribed receipt, payment mode and deductible extent.
Working capital adjustment in transfer pricing may neutralise margin differences arising from inventory, trade receivables and trade payables through the time value of funds. Rule 10B(3) permits adjustment where a difference materially affects price, cost or profit and can be eliminated by a reasonably accurate computation. Verification of the taxpayer's computation and supporting material is required before granting the adjustment. A CSR contribution disallowed as business expenditure may nevertheless qualify for a separate section 80G deduction. An appellate authority may entertain an additional claim arising from facts already on record, subject to verification of the donee's eligibility, payment, prescribed receipt, payment mode and deductible extent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921