Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
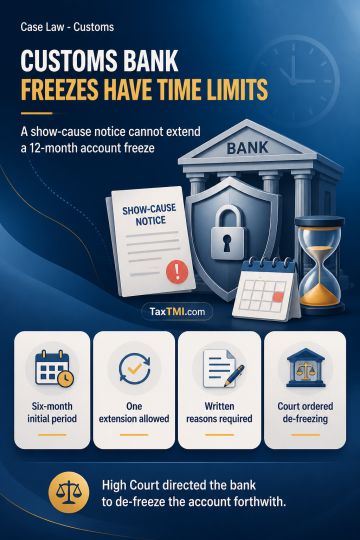
Freezing of a bank account under section 110(5) of the Customs Act may initially continue for six months and be extended once for a further six months only on recorded written reasons. Issuance of a show-cause notice does not preserve investigating authorities' power to continue the freeze beyond the statutory maximum of twelve months. As the maximum period had expired, the High Court found a prima facie basis for de-freezing and directed the bank to de-freeze the account forthwith.
Freezing of a bank account under section 110(5) of the Customs Act may initially continue for six months and be extended once for a further six months only on recorded written reasons. Issuance of a show-cause notice does not preserve investigating authorities' power to continue the freeze beyond the statutory maximum of twelve months. As the maximum period had expired, the High Court found a prima facie basis for de-freezing and directed the bank to de-freeze the account forthwith.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916