GST refunds for cancelled air tickets remain available when passenger reimbursements defeat unjust enrichment and credit-note adjustment is unavailabl...
Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
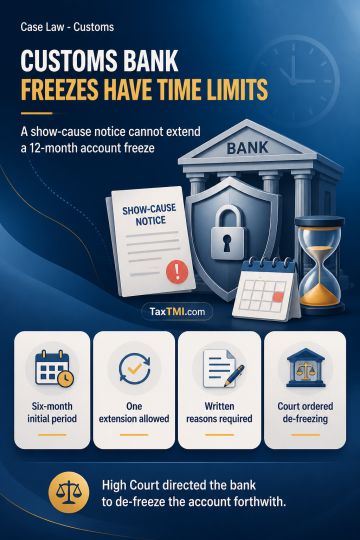
Freezing of a bank account under section 110(5) of the Customs Act may initially continue for six months and be extended once for a further six months only on recorded written reasons. Issuance of a show-cause notice does not preserve investigating authorities' power to continue the freeze beyond the statutory maximum of twelve months. As the maximum period had expired, the High Court found a prima facie basis for de-freezing and directed the bank to de-freeze the account forthwith.
Freezing of a bank account under section 110(5) of the Customs Act may initially continue for six months and be extended once for a further six months only on recorded written reasons. Issuance of a show-cause notice does not preserve investigating authorities' power to continue the freeze beyond the statutory maximum of twelve months. As the maximum period had expired, the High Court found a prima facie basis for de-freezing and directed the bank to de-freeze the account forthwith.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921