Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
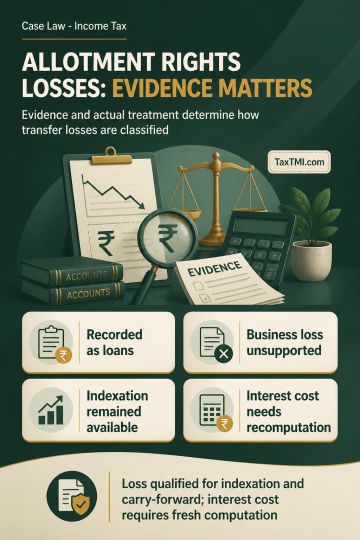
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
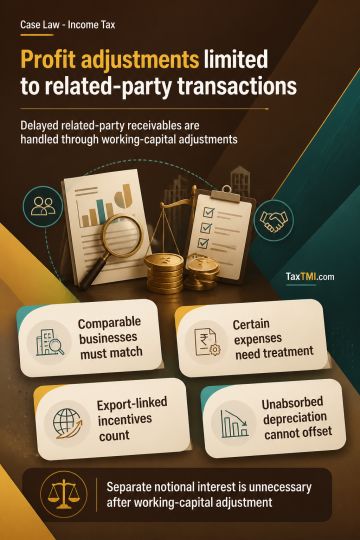
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Non-compliance with import conditions for restricted gold...
Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Non-compliance with import conditions for restricted gold renders the goods prohibited for confiscation purposes, whether the items are treated as gold bars or jewellery. Failure to meet eligible passenger, declaration and permissible-import requirements may support absolute confiscation. Redemption under Section 125 is discretionary rather than a right. Non-declaration, concealment and surrounding circumstances may justify refusal of redemption on payment of fine. Writ review does not ordinarily disturb that discretionary decision unless it is perverse or arbitrary. Absolute confiscation of the gold ornaments and refusal to permit redemption were upheld.
Non-compliance with import conditions for restricted gold renders the goods prohibited for confiscation purposes, whether the items are treated as gold bars or jewellery. Failure to meet eligible passenger, declaration and permissible-import requirements may support absolute confiscation. Redemption under Section 125 is discretionary rather than a right. Non-declaration, concealment and surrounding circumstances may justify refusal of redemption on payment of fine. Writ review does not ordinarily disturb that discretionary decision unless it is perverse or arbitrary. Absolute confiscation of the gold ornaments and refusal to permit redemption were upheld.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916