Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
Money-laundering judgment timing requires awaiting the scheduled-offence decision despite continuation of the underlying trial where outcomes directly...
Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
Page of 4918
Press 'Enter' after typing page number.
101 to 120 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
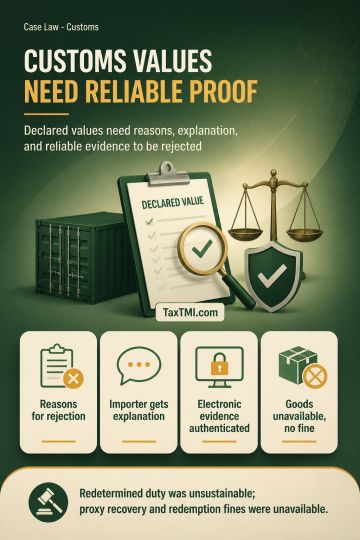
Rule 12 permits rejection of declared customs value only where there is reason to doubt its truth or accuracy, the importer has an opportunity to explain the price, and valuation follows the prescribed method, including contemporaneous import values where relevant. Unsupported intelligence and recovered documents did not establish undervaluation, rendering redetermination and differential duty unsustainable. Electronic data, messages, emails and invoices required statutory certification and reliable authentication; unauthenticated material could not prove undervaluation. Each IEC holder filing its own bill of entry remained the importer liable for duty, preventing recovery from an alleged proxy importer. Goods unavailable for confiscation could not attract confiscation or redemption fine.
Rule 12 permits rejection of declared customs value only where there is reason to doubt its truth or accuracy, the importer has an opportunity to explain the price, and valuation follows the prescribed method, including contemporaneous import values where relevant. Unsupported intelligence and recovered documents did not establish undervaluation, rendering redetermination and differential duty unsustainable. Electronic data, messages, emails and invoices required statutory certification and reliable authentication; unauthenticated material could not prove undervaluation. Each IEC holder filing its own bill of entry remained the importer liable for duty, preventing recovery from an alleged proxy importer. Goods unavailable for confiscation could not attract confiscation or redemption fine.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918